B9: Cash Advance
B9 - Get Your Paycheck EarlyFinanceVerified
- 7.44K Reviews
- 4.6
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
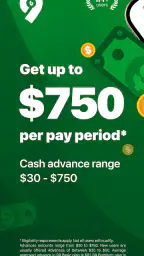
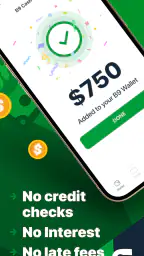
 Analysis by Appwesome
Getting paid on a regular schedule is simple until an unexpected bill arrives at the wrong time. I looked at B9: Cash Advance as a finance app built around that exact gap: helping eligible users access part of their paycheck before payday. It is free to install, aimed at Everyone, and developed by B9 - Get Your Paycheck Early. The idea is easy to understand, but the useful question is whether the experience feels dependable when money is tight, especially when the phone has a weak connection or the user needs an answer quickly.
My overall impression is that B9 is most useful as a short-term timing tool, not as a replacement for budgeting or a general-purpose banking solution. Its appeal comes from convenience: instead of waiting for the normal payday cycle, a user can try to arrange an advance through the app. That can matter when a utility payment, transport cost, or grocery purchase lands a few days too early. At the same time, an advance still has to be repaid or reconciled with future income, so the app makes the most sense when the need is temporary and the next paycheck is reasonably predictable.
How B9 feels when the connection matters
The first setup is more than a quick tap
Because this is a finance service, I would not approach the first launch like a casual calculator or shopping app. The app needs to establish enough information to determine whether its paycheck-advance service fits the user. That means I would set it up when I have a stable internet connection, enough battery, and time to read each screen rather than trying to rush through the process beside a checkout counter.
This is one of the less obvious practical points: connectivity is not merely about loading the interface. A weak connection can interrupt a sign-in step, delay a status update, or leave the user unsure whether an action went through. With a financial app, uncertainty is more uncomfortable than a normal loading delay. I prefer to complete account-related tasks from a reliable home or office network, then use the phone on the move mainly for checking progress and handling straightforward decisions.
The app is currently listed as version 3.70.0 and works on Android 8.0 or later. That broad operating-system reach is helpful for people who keep an older phone, although an older device may still feel slower when several apps are open or when the network changes between Wi-Fi and mobile data. I would close unnecessary background apps before beginning an important request, not because B9 promises a particular performance trick, but because reducing distractions makes it easier to notice whether a screen has actually completed.
What happens in everyday mobile situations
The strongest use case is a short, specific cash-flow problem. Imagine that my paycheck normally arrives at the end of the week, but a necessary car repair appears on Tuesday. I could open B9 from my phone, review the available advance information, and decide whether using part of the upcoming paycheck is sensible. That is more convenient than waiting until I reach a computer, and it fits the way people usually discover urgent expenses: away from a desk and often while already dealing with the problem.
Still, I would avoid making a request from a moving train, a crowded store, or a parking lot with unreliable reception. If the app needs to refresh account information, a broken connection can make a result appear incomplete. The safer workflow is to pause, move somewhere with a dependable signal, and confirm the final status before assuming the money is available.
Other Stories to Read




Mobile convenience also creates a behavioral risk. The phone makes an advance feel close to an ordinary tap-to-pay purchase, even though it affects future income. I found it helpful to decide the repayment plan before opening the app. I would write down the amount needed, the bill it covers, and what remains from the next paycheck. That small pause keeps the tool focused on a genuine timing issue instead of turning it into a habit for routine spending.
Reading the important details before accepting help
A cash advance is not automatically cheap simply because the app itself is free to download. The free label describes access to the application, not a guarantee that every service-related condition will suit every user. Before confirming anything, I would read the amount, timing, repayment expectations, and any applicable terms shown in the current account flow. These details matter more than the convenience of reaching the screen quickly.
This is where B9 differs from a basic overdraft buffer or a credit card. A credit card can provide a reusable line for purchases, while an overdraft may cover a transaction automatically, sometimes with its own bank charges. B9 is centered on getting an advance against pay rather than borrowing indefinitely. That focus can be clearer for a one-off gap, but it also means I would not treat it as a flexible emergency fund that can be used without checking the effect on the next pay cycle.
Another trade-off is predictability. If my income changes often, arrives irregularly, or is already committed to rent and essential bills, an advance may solve today’s problem while creating a tighter week later. In that situation, a spending review, employer assistance, or a conventional savings buffer could be a better answer. B9 is strongest when the user understands exactly what future income is being brought forward.
When the app does not respond as expected
Connectivity problems deserve a deliberate recovery plan. If a screen spins, I would not repeatedly tap the request button. Repeated attempts can create confusion about whether the first action was received, even if the issue is only a delayed response. I would wait, check whether the app shows a changed status, and then reopen the relevant area only after the connection is stable.
If the app closes or the phone switches networks during a request, I would first check the account status rather than starting over. A screenshot of the visible status can also help me remember what happened, although I would avoid storing sensitive financial information in an exposed photo folder. If the status remains unclear, the sensible next step is to use the app’s available support route and describe the time, screen, and connection change without sending unnecessary personal details through an untrusted channel.
This recovery approach is especially important when a user is standing at a checkout and needs immediate certainty. I would never tell a cashier that funds are available based only on an unfinished loading screen. A completed confirmation is a much safer point at which to make a payment decision. If the connection is too poor to establish that confirmation, using another payment method or postponing the purchase is less stressful than guessing.
The same caution applies to logging in again. On a shared or public network, I would avoid saving credentials and would not leave the app open after finishing. Finance apps deserve the same care as online banking, even when the task seems small. B9’s convenience is valuable only if the user protects access to the account and stays alert to unusual prompts or messages.
Using B9 without wasting mobile data
For most people, checking a finance app should not be a heavy data activity, but I still prefer to use Wi-Fi for setup, updates, and any process involving several screens. This is less about a confirmed data figure and more about control: a stable connection reduces the chance of an interrupted request, while Wi-Fi avoids spending mobile data on app maintenance when a home network is available.
On mobile data, I would open B9 only when I need to check a balance-related status or manage a time-sensitive task. I would not leave it running in the background unnecessarily, and I would keep the phone’s operating system and app installation current when practical. Updates can improve compatibility, but I would install them before an emergency rather than moments before I need an advance.
A useful habit is to separate browsing from action. I can review what I need and decide the amount before opening the request flow. That limits the time spent connected and, more importantly, prevents an impulsive choice made because the app is already open. I would also avoid using unsecured public Wi-Fi for sensitive account work. If mobile reception is poor, waiting for a trusted network is preferable to exposing financial activity on a connection I do not control.
Who will get the most from it
B9 is a good fit for someone with regular pay who occasionally faces a mismatch between an unavoidable expense and the normal payday. The app’s store presence reflects substantial adoption, with over one million installs, an average rating of 4.6 from around eighteen thousand ratings, and roughly seven thousand four hundred written reviews. Those figures suggest that many people find the concept useful, although they should not replace checking whether the service matches an individual’s income pattern and financial priorities.
I can also see value for a user who wants a focused alternative to carrying a credit-card balance. Bringing forward a limited amount tied to a known paycheck may feel easier to reason about than rolling an open-ended purchase balance from month to month. The advantage disappears, however, if the user repeatedly needs advances to cover ordinary expenses. Repeated use is a sign that the underlying budget needs attention, not proof that the next advance will solve the problem.
I would skip B9 if I have unpredictable income, no clear plan for the next paycheck, or a habit of using short-term borrowing for discretionary purchases. I would also compare other options if my bank already offers a transparent, low-cost overdraft arrangement or if I have emergency savings that can cover the expense without affecting future income. A different option may be better when the priority is building long-term financial stability rather than bridging a few days.
What the ratings and presentation tell me
The app is free and carries an Everyone content rating, which makes it approachable from an installation standpoint. That does not make every financial decision suitable for every age or situation, so I would still expect an adult user to understand the obligations connected with an advance. The developer name, B9 - Get Your Paycheck Early, makes the central purpose clear without pretending that the app is a full financial-planning suite.
The rating profile is encouraging, but finance reviews need to be read differently from game reviews. A positive score can reflect a smooth sign-up or a helpful moment during an emergency, while another user may have different expectations about eligibility, timing, or account handling. I would use the rating as a reason to investigate B9, not as a promise that an advance will be available exactly when I want one.
One practical tip is to review the service during a normal week before relying on it during an emergency. That gives me time to understand the navigation, connection behavior, and status language without a bill waiting in the background. It also lets me decide whether the app feels clear enough for stressful situations. If I find the terms confusing when calm, I would not depend on it when rushed.
My connectivity verdict
B9: Cash Advance works best when its mobile convenience is paired with disciplined timing. I like the idea of handling a paycheck gap from a phone, and the app is more focused than a general credit product when the need is specifically about receiving income earlier. Its free installation, broad Android compatibility, and strong user response make it worth considering for people whose pay schedule is dependable.
My reservation is not about the basic concept; it is about the consequences of treating quick access as effortless money. A weak connection can make an urgent decision harder, and a strong connection cannot remove the need to understand repayment. I would use trusted Wi-Fi for setup and important account actions, avoid repeated taps during a delay, confirm the final status before spending, and decide the repayment amount before requesting anything.
In the end, I would recommend B9 to a friend only for a defined, short-lived cash-flow gap with a realistic plan for the next paycheck. I would not recommend it as a substitute for savings, a permanent response to overspending, or a reason to ignore cheaper alternatives. Used carefully, it can be a practical bridge. Used automatically whenever money feels tight, it may simply move the pressure forward.
Highlights
- Fast application process with quick eligibility decisions
- No traditional credit check required for many applicants
- Clear repayment schedule shown before accepting an advance
- Useful for covering unexpected short-term expenses
- Funds can be sent directly to a linked bank account
Limitations
- Advance limits may be low for new or occasional users
- Express funding and optional services may involve extra fees
- Repayment is often due on the next scheduled payday
- Late repayment can lead to additional charges or account restrictions
- Availability and terms vary by state and user eligibility
Frequently Asked Questions
01What is B9: Cash Advance, and how does it work?
B9: Cash Advance is a financial app designed to help eligible users access part of their expected income before payday, along with banking-style features such as direct deposit and spending tools. After creating an account, you may need to verify your identity and income. Available advance amounts, repayment conditions, subscription costs, and other features can vary by user and location.
02How much money can I receive through B9: Cash Advance?
The amount available through B9 depends on factors such as your account activity, income, direct-deposit history, eligibility, and repayment record. New users should not assume they will receive the maximum advertised amount immediately. The app normally displays your personal limit before you accept an advance, so review that offer carefully and confirm the total amount you will owe.
03Does B9 charge fees or require a subscription?
B9 may use a membership or subscription model, and additional charges can apply depending on how you access or receive funds. Before signing up or requesting an advance, check the current pricing page and the final confirmation screen for membership fees, expedited-transfer charges, late-payment consequences, and any other applicable costs. Terms may change, so avoid relying only on older reviews.
04How quickly can a B9 cash advance reach my bank account?
Transfer speed depends on the method selected, your bank, account verification, weekends or holidays, and whether you qualify for an instant delivery option. Some transfers may arrive quickly, while standard delivery can take longer. B9 should show an estimated arrival time before you confirm the request, but estimates are not always guarantees, especially during bank processing delays.
05Is B9: Cash Advance safe, and what should I know before downloading it?
B9 handles sensitive information, including identity and financial details, so download it only from the official Google Play Store or Apple App Store and review the requested permissions. Use a strong password and enable available security protections. Also read the privacy policy, membership terms, repayment rules, and eligibility requirements, because a cash advance is not free money and may affect your budget if repayment is due quickly.


